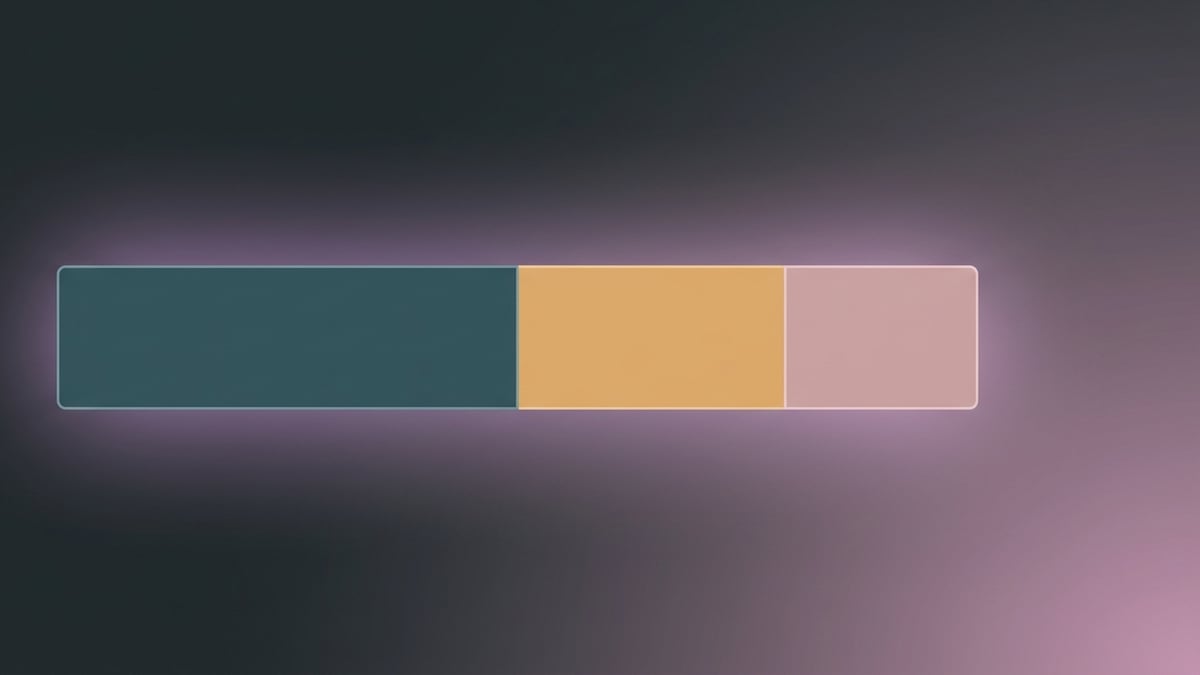
The 50/30/20 Rule: A Budget That Actually Sticks
The 50/30/20 budget rule explained for real life. A step-by-step way to split your paycheck so you can save without hating the process.
Quick answer: The 50/30/20 rule splits your after-tax paycheck into three buckets: 50% needs, 30% wants, and 20% savings and debt paydown. It works because it’s simple enough to follow on a Sunday afternoon, flexible enough to survive an irregular month, and built around a single decision (what bucket does this expense belong to?). On a $5,000 monthly take-home, that’s $2,500 needs, $1,500 wants, and $1,000 future-you.
Table of contents
- What is the 50/30/20 rule?
- How to apply it: $4K, $6K, $10K examples
- The needs vs wants gray zone
- When 50/30/20 breaks
- 5-step setup (30 minutes)
- Common mistakes
- FAQ
- Practice in UseFinLit
What is the 50/30/20 rule?
The 50/30/20 rule is a budget formula that splits your after-tax (take-home) income into three buckets:
- 50% Needs: rent or mortgage, groceries, utilities, insurance, transportation, minimum debt payments.
- 30% Wants: dining out, streaming subscriptions, hobbies, vacations, premium phone plans, the gym you actually use.
- 20% Savings and debt paydown: emergency fund, retirement (401k, Roth IRA), brokerage account, extra debt payments above the minimum.
The rule was popularized in 2005 in All Your Worth: The Ultimate Lifetime Money Plan by then-Harvard professor Elizabeth Warren and her daughter Amelia Warren Tyagi. The concept was originally meant to help middle-class American families avoid lifestyle creep, the slow drift where every income raise gets absorbed by upgraded wants.
Why it stuck: Most budget systems fail because they ask you to track 40+ categories. The 50/30/20 rule asks you to make exactly one decision: is this expense a need, a want, or savings? That single question is the entire system.
A 2023 NerdWallet survey of 1,400 adult budgeters found that simple-bucket systems (50/30/20 and similar) had a 12-month adherence rate of 52%, roughly double the 24% adherence rate of detailed-category budgeting apps.1
How to apply it: $4K, $6K, $10K examples
After-tax monthly income is what matters. If you make $80,000/year gross with ~$60,000 net (after federal, state, FICA), your monthly take-home is $5,000.
Here’s how the buckets look at three income levels:
| Take-home/month | Needs (50%) | Wants (30%) | Savings (20%) |
|---|---|---|---|
| $4,000 | $2,000 | $1,200 | $800 |
| $6,000 | $3,000 | $1,800 | $1,200 |
| $10,000 | $5,000 | $3,000 | $2,000 |
A practical translation of $5,000/month with the rule:
Needs ($2,500):
- Rent / mortgage: $1,400
- Groceries: $400
- Utilities (electric, internet, water, gas): $200
- Health insurance premium: $200
- Transportation (car payment + insurance OR transit): $250
- Minimum debt payments: $50
Wants ($1,500):
- Dining out / coffee: $300
- Streaming + entertainment: $50
- Hobbies / shopping: $400
- Travel fund: $250
- Subscriptions / gym / extras: $100
- Buffer / “fun money”: $400
Savings ($1,000):
- Roth IRA contribution: $500
- 401(k) above match: $200
- Emergency fund top-up: $200
- Brokerage / investing: $100
The needs vs wants gray zone
The hardest part of 50/30/20 isn’t the math. It’s the philosophy. Where does the $200 phone plan go? The gym membership you use twice a week? The car that’s nicer than you needed?
A useful framework: the “stripped-down version” test. For any expense, ask:
“Could I survive this month with the cheapest version of this thing?”
If yes, the difference between your actual choice and the stripped-down version is the want portion.
Example: phone plan.
- Stripped-down: $30/month prepaid plan. That’s a need.
- Premium plan: $90/month. The extra $60 is a want.
This split lets you say “I have an iPhone” without pretending it’s all need or all want. It’s $30 need plus the rest a want. Apply this to gym ($30/month basic gym vs $200/month boutique class), housing ($1,200 small apartment vs $1,800 nicer building), and so on.
A 2024 Acorns study of 2,800 millennial budgeters found that the average household had 18% of expenses miscategorized: items called “needs” that were actually upgraded versions of needs. Re-categorizing recovered an average of $340/month for savings.2
When 50/30/20 breaks
The rule isn’t universal. It breaks in three common situations:
Low-income households (sub-$3,000/month take-home)
When 50% of your income barely covers actual rent and food, there’s no flex. Forcing 30% into wants and 20% into savings creates a structural impossibility.
Alternative: the 70/20/10 rule (70% needs, 20% savings, 10% wants) for households where rent eats more than 40% of gross income. Acknowledge the constraint, focus on saving any small amount.
High-cost cities (NYC, SF, LA, Boston, Seattle)
If you live in NYC paying $3,200 for a one-bedroom on a $7,000 take-home, your “need” line is already 46% before factoring in groceries and transit. The rule still works directionally, but the percentages flex.
Alternative: use 60/20/20 in expensive cities. Accept that geography costs you a savings rate, then trade it for career opportunity that ideally compounds the income.
High-debt situations (credit card debt over $10K)
If you’re paying 24% APR credit card interest, mathematically nothing else compounds faster than paying it down. Putting 5% in a savings account while paying 24% on credit card balances loses money every month.
Alternative: the avalanche approach. Knock down high-interest debt first (50% needs, 50% debt plus minimum savings), then return to 50/30/20 once debts are at 0% to 12% APR levels.
5-step setup (30 minutes)
This is your weekend afternoon plan. You’ll need: 30 minutes, last 2 months of bank/credit card statements, a notebook or spreadsheet.
Step 1: Find your take-home (5 min) Look at your last 2 paychecks. The number that hits your bank account is take-home. Multiply by pay period frequency (× 2 if biweekly, × 26 / 12 if biweekly normalized). That’s your monthly take-home base.
Step 2: Pull last 2 months of expenses (8 min) Download CSV from your main bank and credit cards. Don’t categorize yet, just sum the totals. Confirm: net take-home minus total expenses equals positive (saving) or negative (in debt). This is your reality check.
Step 3: Bucket every expense (12 min) Go through line by line. Each row gets one tag: N (need), W (want), or S (savings, meaning the amount transferred to a savings or investment account). Use the stripped-down test for borderline items.
Step 4: Calculate your current % split (3 min) Sum each bucket. Divide by take-home. Example: if you spent $3,500 on needs and your take-home was $5,000, your “needs” line is 70%, significantly above the 50% target.
Step 5: Pick ONE bucket to fix (2 min) Don’t try to fix all three at once. Pick the one furthest from target. If wants are 35% (vs 30% target), a 5-point fix means cutting roughly $250/month. Pick 2-3 specific subscriptions or recurring categories to cut. Set a calendar reminder for 30 days to re-check.
Common mistakes
Mistake 1: Counting groceries as 100% need. Some groceries are needs (rice, eggs, vegetables). Premium organic, specialty cheeses, pre-made meals are wants. Crude split: 70% of your grocery spend is need, 30% is want.
Mistake 2: Counting all of housing as a need. Stripped-down version test: a small apartment in your city is the need. The upgraded version is partial want.
Mistake 3: Putting all extra cash into “savings”. Savings is not a checking account earning 0.01%. Savings means HYSA (high-yield savings, 4-5% APR) or invested. Otherwise inflation erodes it.
Mistake 4: Treating the rule as monthly when income is irregular. Freelancers, sales-commission workers, and gig workers should average over 3 to 6 months and use the average as the baseline.
FAQ
Does 50/30/20 work on every income level?
Not exactly. On take-home below $3,000/month, the math gets tight. Needs alone often exceed 60-70% in expensive cities. In that case, use 70/20/10 (70 needs, 20 savings, 10 wants) until income grows. The key is to keep some savings, even 5%, rather than zero.
Is 50/30/20 better than zero-based budgeting?
It depends on personality. Zero-based budgeting (every dollar assigned a job before the month starts) is more precise and saves more if you stick with it, but adherence is harder. 50/30/20 is the “Pareto-optimal” of budgeting: 80% of the savings impact for 20% of the effort. Most people fail zero-based. Most who try 50/30/20 stick with it for at least 6 months.
Where does retirement contribution fit?
Inside the 20% savings bucket. If your employer offers 401(k) match, prioritize that match first (free money), then Roth IRA, then taxable brokerage. The 20% target is meant to include retirement contributions, not stack on top of them.
What if my employer-matched 401(k) is already deducted before take-home?
If your gross is $7,000 and 6% goes to 401(k) before you see it, your take-home is calculated on the post-deduction number. The 401(k) contribution is already savings; it’s just outside the 20% bucket of your remaining take-home. Some budgeters add it back. “True savings rate” = (401(k) % + Roth + brokerage) / gross income. That number above 20% means you’re on track.
Are bills (electric, internet) part of the 50% or outside?
Inside the 50%. Recurring necessary bills are needs. Premium internet (gigabit when 100mbps would do) has a wants portion via the stripped-down test.
Should I keep emergency fund inside savings or separate?
Mentally separate, physically the same. Most budgeters keep emergency fund in a separate HYSA so they don’t accidentally spend it. The 20% savings bucket flows into emergency fund first (until 3-6 months of expenses), then into investing.
Can I use 50/30/20 if I have student loans?
Yes. Minimum loan payments are needs (50% bucket). Anything above the minimum is debt paydown that counts in the 20% savings bucket. If your APR is above 7%, prioritize paying down before investing in taxable brokerage. If below 5%, invest while paying minimums and let compounding do the work.
Practice the 50/30/20 Rule in UseFinLit (1 minute)
Reading about the rule is one thing. Applying it to your actual numbers is another. UseFinLit’s Module 1 / Lesson 3 walks you through the same exercise interactively in 60 seconds. You input your take-home, the app shows you the three buckets, and a 5-question quiz tests whether you’d categorize 5 expenses correctly. Then you unlock the rest of the budgeting module.
UseFinLit: 1-minute lessons, 100K paper-trading, AI feedback on every trade. 32 modules, 600+ lessons, NYSE, NASDAQ, and Borsa Istanbul live data.
Educational only. Not financial advice. Tax and investing rules vary by state and circumstance; consult a qualified advisor for your situation.
Read Next
- What is a Budget and Why It Changes Your Life: start here if budgeting is new
- Needs vs Wants: 12 Questions That Trick Your Brain: the philosophy behind the buckets
- Your First $1,000: A 30-Day Savings Sprint: what to do with your 20%
- The Magic of Compound Interest: why the 20% matters most
- Budgeting & Saving Pillar Guide: the full year-1 roadmap
Author: Sarah M., Personal Finance Editor at UseFinLit. Former Wall Street Journal contributor on personal finance. Has been running a 50/30/20 budget for 11 years (with the occasional 50/35/15 month).
Published: May 29, 2026 · Last updated: May 29, 2026